Skip to content
Humans in the Boardroom #7

The UK Government is consulting on modernising corporate reporting, including simplifying the statutory requirements for board remuneration disclosures. Remuneration reports have indeed become too long, repetitive and bureaucratic, more likely to obscure the real issues than help investors understand them. But there are bigger questions that are not being answered by remuneration reports.
I would simplify the disclosure requirements to answering three questions:
- How much are we paying, and how much could that pay become?
- Why have we chosen those amounts?
- What risks are we creating?
How much?
It can be complicated calculating how much might get paid out, but it is not difficult to make a set of assumptions, declare them and then calculate the resulting pay. The Committee should show a range of outcomes, including the highest and lowest remuneration individuals could receive. This gives a good understanding of the potential costs and effect of different assumptions.
Why?
Remuneration Committees should be able to explain why they have chosen a particular level of pay. They might, for example, quote comparative pay studies, need for retention, other metrics or even just inflationary increases.
Risks?
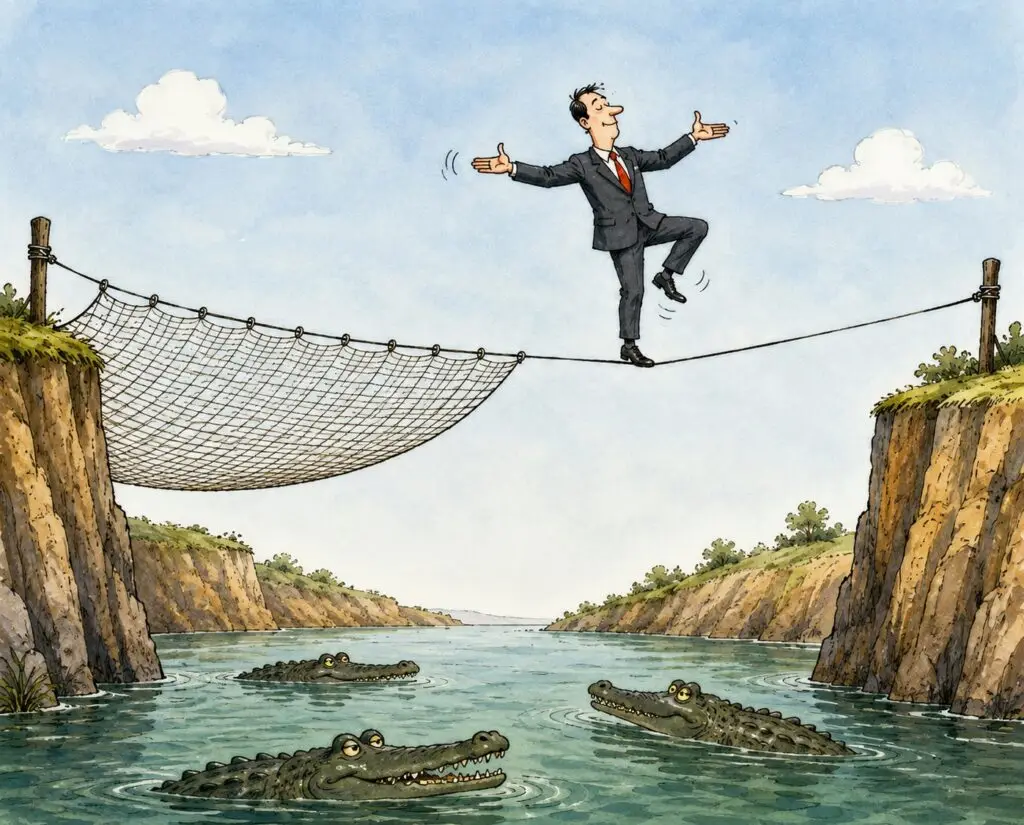
This is the key question that often gets ignored. We talk about remuneration as an incentive, but if you pay an executive a large bonus for achieving a particular objective, you are clearly expecting them to work very hard to achieve it. That is the point of the incentive.
But what happens when the executive starts to see barriers to achieving them? I’ve seen executives pursue profit targets while cash deteriorated, meet earnings expectations while customer service suffered, or push transactions through despite growing concerns about their quality. An executive whose bonus depends heavily on hitting an annual profit target will, for example, be tempted to cut maintenance spend, delay expenditure, review asset lives, push marginal sales or recognise income early.
I am not arguing against offering big bonuses, but they do need to be risk assessed like any other material company initiative. Mitigations might include increased audit review, more reporting or malus/clawback if unethical behaviour is discovered.
An autocratic leader with a large bonus opportunity creates particular risk. The steep authority gradient can make it difficult for directors to challenge that executive, so increasing the risk of dysfunctional behaviour going unchecked.
A board might ask itself about its remuneration schemes:
- Do they put undue weight on a few measures that might deprioritise others (eg profit over cash, or earnings over customer service)?
- Might they put excessive weight on one time period, encouraging short-termism?
- Could they encourage unethical behaviour as a means to an end?
- Are they so heavily weighted to a small number of executives (or perhaps even just one) that they risk undermining teamwork beneath them?
- Are they so complex that they might not really incentivise the target outcomes?
- Do they do enough to retain key employees, particularly when bonuses aren’t being paid out?
The first two questions are particularly important, because a perfectly legitimate target can distort behaviour if it gives too much weight to one measure or one time period.
The value of these questions does not come from just listing risks, it comes from the discussion and preparations made to mitigate them.
Takeaway
Reducing boilerplate disclosure is a good start, but the remuneration issue is not just how much directors are paid. It is why they are paid that way, what behaviours are being encouraged, and whether the Board has properly considered those risks.
We often talk about remuneration as an incentive, yet rarely ask what exactly is being incentivised? If a pay structure pushes executives hard towards a target, the Board should be equally clear about the risks created along the way.
Every pay packet sends a signal. Boards need to be sure it is the right one.
________________________________________________________
This is the seventh in my newsletter series, Humans in the Boardroom. If you enjoyed this article, you can subscribe on LinkedIn for future editions exploring human performance, leadership and decision-making in the boardroom.
Previous newsletters are available here:
What BP’s board problem tells us about the human side
Tennis shows similar human behaviours to the boardroom
#3 – Not so Pretty Polly
From City darling to prison – how Polly Peck collapsed
#4 – Hidden Risks of Successful Leaders
Can success contain the seeds of destruction?
#5 – What’s in a name?
Psychological labels distract from understanding behaviour
#6 – Overconfident? Of course not
Overconfidence is a very common source of failure